A letter of authority lets a financial adviser collect policy information directly from a client’s existing providers. The hard part is what happens after the responses come back. Each provider answers in its own format, with valuations on different dates and guarantees described in its own wording. The fix is to decide in advance which data points you need, extract each one once into a standard structure, flag any gaps before anyone starts writing, and then build both the comparison and the suitability report from that single set of data. When you do it that way, you stop retyping figures, guarantees stop slipping through, and the comparison actually answers the question the client needs answered.
This guide covers what to ask for, where comparisons usually go wrong and a workflow that cuts out the rekeying without cutting corners.
1. What a letter of authority does in the advice process
The short answer: A letter of authority (LOA) is a document signed by the client that authorises their existing pension, investment or insurance providers to release information to their financial adviser. It allows the adviser to collect values, charges, fund details, guarantees and benefit options directly from the provider. It doesn’t let the adviser make changes or transfer anything.
Most firms send LOAs at the start of a pension review, a consolidation or a retirement income case. The information that comes back is the factual basis for the advice. If it’s incomplete, the advice is built on assumptions.
A few practical points catch people out. Some schemes only accept an LOA dated within a recent window. Buckinghamshire’s Local Government Pension Scheme, for example, asks for one dated within 3 months of the request. Many providers also write to the client directly to confirm that an adviser has been in touch. That’s sensible for security, but it can add days if the client doesn’t respond.
2. Why the LOA stage still slows cases down
The LOA stage is usually the longest wait in a pension case, and the reason is mostly mechanical. Requests go out by email, post or provider portals. Some come back quickly and complete. Others come back partial, a few never come back without a phone call, and each response arrives in a different layout.
The industry has been working on this. Origo extended its Unipass Letter of Authority service across the whole market, giving advisers 1 standardised request form that can go to several providers and platforms. It also added a checklist so advisers can specify exactly which data points they need. Scottish Widows, Aviva, Royal London and Legal & General have formed a consortium with Origo to improve digital LOA processing. Scottish Widows has said its aim is LOA responses in 15 minutes rather than 15 days.
That’s real progress, but it doesn’t remove the work at your end. A faster response is still a PDF or a data sheet that someone has to read, understand and turn into a comparison.
Pensions dashboards won’t remove it either. All in-scope schemes had to be connected by the statutory deadline of 31 October 2026, but dashboards are designed to help people find pensions and see headline values. They’re not designed to give you exit charges, guaranteed annuity rate conditions or protected tax-free cash. For advice, the LOA response is still what you rely on.
What to ask for, so the comparison works first time
The short answer: Ask every provider for the same set of data points, so that every response can be compared side by side. That means the plan type, current and transfer values with dates, charges including exit fees, fund holdings, contributions, guarantees and protections, death benefits, retirement options and any restrictions on transfer.
Most incomplete comparisons start with a vague request. “Please provide full details of the plan” invites the provider to decide what full means. A specific checklist doesn’t.
Your standard request should cover:
- Plan Type And Policy Number
- Current Value And Transfer Value With Dates
- All Charges Including Exit Fees
- Fund Holdings And Asset Allocation
- Current Contributions And Employer Input
- Guaranteed Annuity Rates And Conditions
- Protected Tax-Free Cash Or Protected Pension Age
- With-Profits Terms And Any Market Value Reduction
- Death Benefits And Nomination Details
- Drawdown And UFPLS Availability
- Pension Sharing Or Earmarking Orders
- Any Other Restrictions On Transfer
Each item is there for a reason. The table below shows why each one matters and what usually goes wrong.
| Data point | Why it matters for the comparison | What often goes wrong |
| Transfer value and date | The comparison must use like-for-like dates | Mixing a value from March with one from October |
| Exit charges | Can make a transfer uneconomic | Recorded as “none” when the provider didn’t answer |
| Guaranteed annuity rate | Can be worth far more than the fund suggests | Rate shown, but the conditions and dates left out |
| Protected tax-free cash | Can be lost permanently on transfer | Not asked for on older policies |
| With-profits terms | Market value reductions can reduce the transfer value | Guaranteed bonuses and terminal bonus not separated |
| Death benefits | Matters more ahead of the 2027 IHT change | Nomination status left unchecked |
| Flexible access options | Shows whether drawdown is possible without moving | Assumed rather than confirmed |
| Sharing or earmarking orders | Affects what the client can actually do | Not asked about at all |
Where pension comparisons most often go wrong
The most common failure is mistaking a gap for a “no”. If a provider doesn’t mention a guaranteed annuity rate, that doesn’t mean there isn’t one. It means the question wasn’t answered. A good comparison records “not confirmed” and sends a follow-up, rather than leaving the cell blank or writing “none”.
This matters because of what’s at stake. When the FCA reviewed retirement income advice files in its thematic review TR24/1, loss of guarantees and features was 1 of the problems it identified. In most of those cases the guarantee was there in the provider’s information. It just wasn’t picked up or given enough weight.
Guarantees can also change who’s allowed to advise. Under the Pension Schemes Act 2015, members with safeguarded benefits worth more than £30,000 must take FCA-regulated advice before transferring or converting those benefits to access them flexibly. Safeguarded benefits include some guaranteed annuity rates. The government’s factsheet on pension benefits with a guarantee explains how this works. An LOA response that turns up a guarantee could change the scope of the case, so you want to know about it on day 1 rather than at the compliance check.
Exit charges are less dramatic but still worth checking. The FCA capped early exit charges at 1% on existing contract-based personal pensions for members aged 55 and over, and pensions taken out after March 2017 can’t have them at all. Older occupational arrangements and with-profits policies can still have their own penalties, and a market value reduction isn’t the same as an exit fee. A comparison should show each of these separately.
Dates are the other quiet problem. If 1 valuation is 6 months older than the rest, the comparison isn’t comparing like with like. Make sure every figure carries its date, and refresh any value that’s out of date before the comparison is finalised.
A workflow that stops you retyping every figure
The short answer: Treat the LOA responses as source documents, not as text to copy. Extract each data point once into a standard structure, check it against the source, flag anything missing, and then let the comparison table and the suitability report both draw from that structured data. A figure is typed or checked once and then used everywhere it’s needed.
Here’s how that looks in practice.
Step 1: Fix your data structure before the responses arrive. Use the same fields, in the same order, for every plan. That’s your checklist from the section above. It becomes the template for both the comparison and the report.
Step 2: Extract once, and keep a link to the source. As each response arrives, pull the data into the structure and note the page or section it came from. When a reviewer later asks where a figure came from, the answer should take seconds to find.
Step 3: Separate “not applicable”, “not confirmed” and “confirmed none”. These 3 statuses mean very different things, and treating them as the same is how guarantees get missed.
Step 4: Chase gaps before drafting. If a guarantee or an exit charge isn’t confirmed, follow it up before anyone starts writing the report. It’s much easier to fix a gap at this stage than to rewrite a report later.
Step 5: Populate the comparison and the report from the same data. If the transfer value appears in the comparison table, the recommendation section and the costs section, it should come from 1 source and be identical in all 3 places.
Take a client aged 58 with 4 old pensions: a 1990s with-profits retirement annuity contract, 2 workplace pots and a stakeholder plan. Done by hand, that can mean 4 different documents, 4 sets of terminology and the same figures typed into a spreadsheet, a comparison table and a report. Done the structured way, each figure is captured once. The retirement annuity contract’s guaranteed annuity rate is flagged as a key feature the moment it’s found, and the comparison is ready for checking rather than for building.
Having written thousands of suitability reports ourselves, we know the LOA stage is often where a case stalls. Usually it’s not the chasing that drags, but the rekeying and reformatting once the information is in.
What the comparison should show your client
A pension comparison is a working document for you, but your client also needs to understand it. Under the Consumer Duty’s consumer understanding outcome, a dense grid of policy data that the client can’t follow doesn’t really meet the standard.
The client-facing version should make 3 things obvious: what they have now, what they’d gain by changing and what they’d give up. Valuable features such as a guaranteed annuity rate or protected tax-free cash deserve their own clear sentence, not a cell in row 14. Where you’re recommending keeping a plan, the comparison should make that reasoning just as visible as a recommendation to transfer.
Where AI helps with LOA data, and where it doesn’t
Pulling data out of inconsistent provider documents is exactly the repetitive work AI handles well. Good paraplanning software can read PDF, Word, Excel and CSV LOA responses, put the data into a consistent structure and populate a comparison table in your firm’s format. That saves the copy-and-paste step that eats the time.
What it shouldn’t do is decide what a missing answer means, or whether a guarantee is worth giving up. Those are judgement calls, and they stay with the paraplanner and the adviser. The most useful setup is one where the AI flags gaps and guarantees clearly, so the reviewer spends their time on the points that matter.
Ammonite states that Planbot makes LOA summaries, pension comparisons and compliance checks up to 90% faster. It works from your firm’s own templates, users can point it at specific pages in a provider document, and it builds tables and calculations from the source data. Because the same data then feeds the report, the suitability report software side isn’t rekeying the figures a second time. It’s also why an AI suitability report generator only works well when the data underneath it is structured properly first.
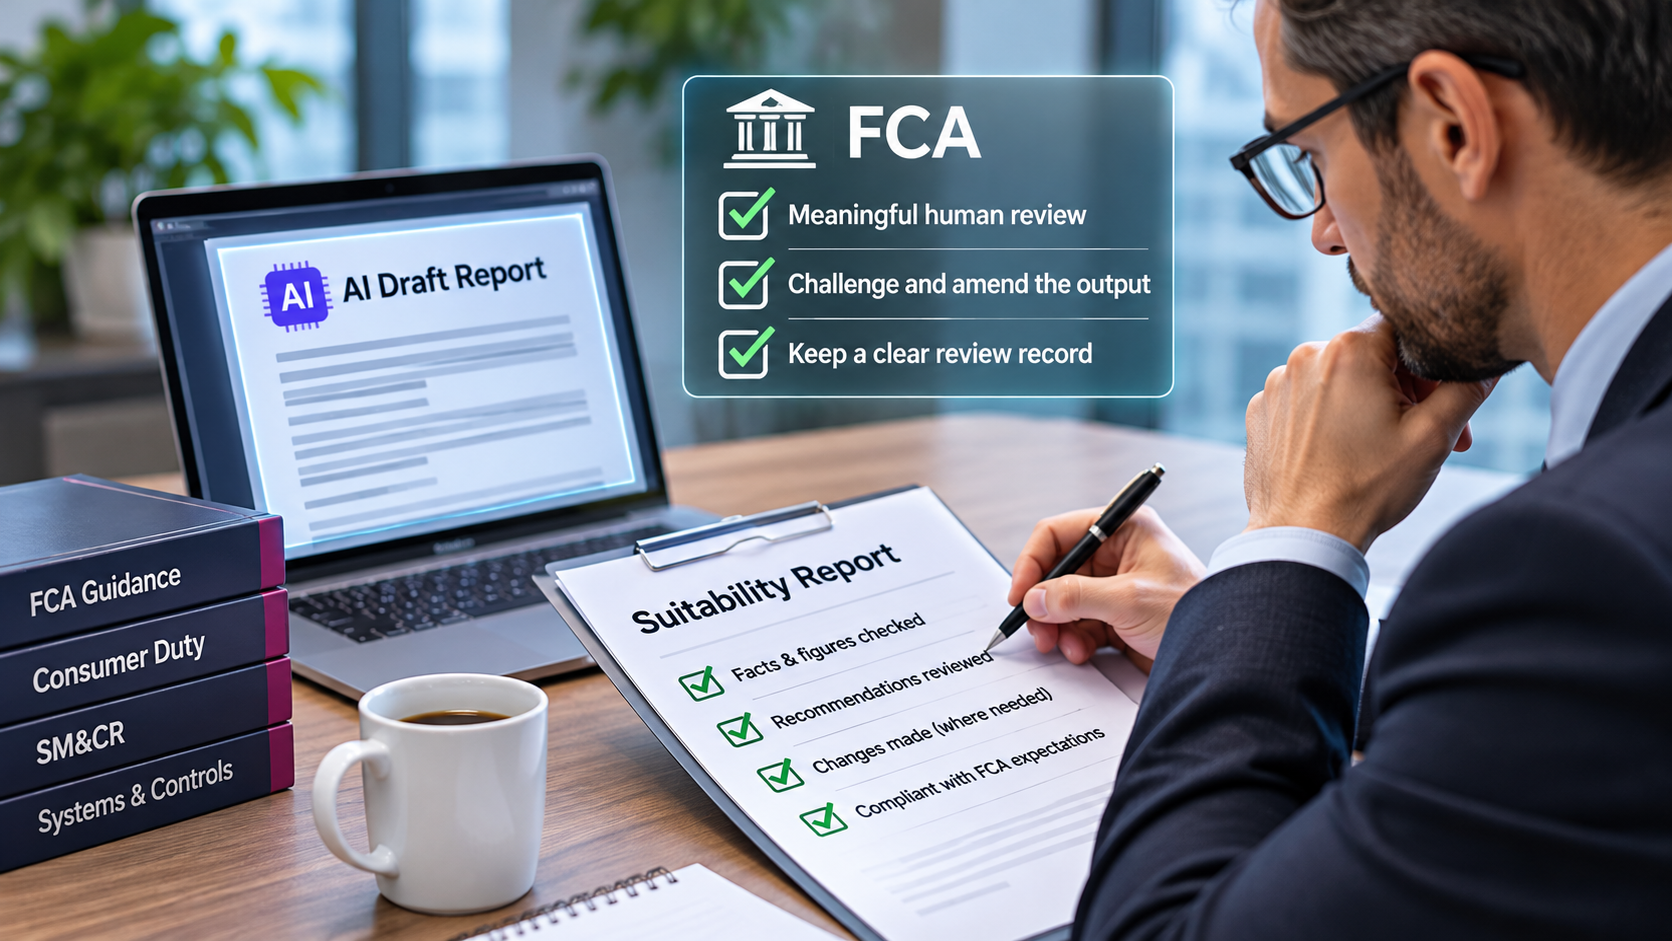
For paraplanning teams handling heavy volumes of consolidation and retirement cases, AI for paraplanners is most useful at this exact point in the workflow, between the LOA arriving and the draft being written. If you’re comparing tools, our overview of AI software for financial advisers is a useful place to start. The FCA expectations on AI in financial advice are worth reading too, because accountability for the output stays with your firm whatever tool produced it. If you need to justify the investment, our guide to the business case for AI in your advice firm shows how to measure the hours that LOA processing currently takes.
See how Planbot turns LOA responses into a comparison
If your team is still copying LOA figures into spreadsheets before anyone can start the report, it’s worth seeing a different way of working. Planbot builds your firm’s LOA summary and pension comparison templates into AI-powered documents, populates them from the provider responses you already receive, and leaves every figure for your paraplanners to check before it moves on. No client data is stored or used to train AI models.
Book a demo and see how your own LOA and comparison templates could work in Planbot.